Wealth Management & Advisory Services
Finding and Working with a Financial Advisor
Wealth management and financial advisory services play a crucial role in helping individuals achieve their long-term financial goals. These services provide expert guidance on investments, taxes, estate planning, retirement planning, and other financial matters. Whether you’re just starting to accumulate wealth or managing a substantial portfolio, working with a financial advisor can provide personalized advice to maximize your financial potential. This chapter will explore how to find and work with a financial advisor, the differences between robo-advisors and traditional financial planning, and the importance of portfolio management and rebalancing.
Finding and Working with a Financial Advisor
A financial advisor is a professional who provides guidance on financial matters, helping you develop strategies to achieve your financial goals. Whether you’re looking to invest, plan for retirement, or manage debt, a financial advisor can help provide direction and expertise.
Types of Financial Advisors:
- Certified Financial Planner (CFP): A CFP is a professional who has completed rigorous training and certification in areas like financial planning, retirement, estate planning, and insurance. They are fiduciaries, meaning they are legally required to act in your best interest.
- Registered Investment Advisor (RIA): RIAs provide personalized investment advice and manage portfolios. They are required to act as fiduciaries, ensuring that their recommendations align with your financial needs.
- Robo-Advisor: Robo-advisors are digital platforms that provide automated, algorithm-driven financial planning services with little to no human intervention. They usually come with lower fees and are often used by individuals with smaller portfolios or those seeking a hands-off investment approach.
- Wealth Manager: A wealth manager typically works with high-net-worth individuals, providing comprehensive financial services including investment management, tax planning, estate planning, and more. Wealth managers may charge higher fees but provide a holistic approach to managing wealth.
How to Choose a Financial Advisor:
When choosing a financial advisor, it’s important to find someone whose expertise aligns with your needs. Here are a few steps to help you choose the right advisor:
- Define Your Financial Goals: Understand what you want to achieve. Are you primarily focused on investment management, retirement planning, or estate planning? Clarifying your objectives will help you select an advisor with the right specialization.
- Check Qualifications and Credentials: Ensure the advisor holds the proper certifications and licenses. For example, a CFP is a respected credential, and a fiduciary advisor is legally required to act in your best interest.
- Understand the Fee Structure: Financial advisors typically charge fees in one of three ways:
- Fee-Only: The advisor charges a flat fee or hourly rate and does not receive commissions from product sales.
- Commission-Based: The advisor earns commissions on the financial products they sell, which may lead to potential conflicts of interest.
- Fee-Based: A combination of a flat fee and commission-based income.
- Interview Multiple Advisors: It’s helpful to meet with several advisors before making a decision. Ask about their approach, fees, and experience. A good advisor should be willing to explain complex financial concepts in an understandable way.
- Consider Compatibility: It’s essential to find someone you trust and feel comfortable with. Financial planning is a long-term partnership, and having a positive working relationship is crucial for your financial success.
Working Effectively with a Financial Advisor:
Once you’ve chosen an advisor, it’s important to work collaboratively to achieve your financial goals. Here’s how to make the most of your relationship:
- Be Transparent: Share your financial situation, goals, risk tolerance, and any other relevant details with your advisor. The more they understand about your circumstances, the better they can tailor their advice.
- Stay Informed: While your advisor provides guidance, it’s important to stay informed about your financial plan and investments. Ask questions if something is unclear and ensure that your strategy is aligned with your goals.
- Review Regularly: Financial planning is an ongoing process. Meet with your advisor regularly (e.g., annually or semi-annually) to review your progress, adjust your goals, and rebalance your portfolio as necessary.
Robo-Advisors vs. Traditional Financial Planning
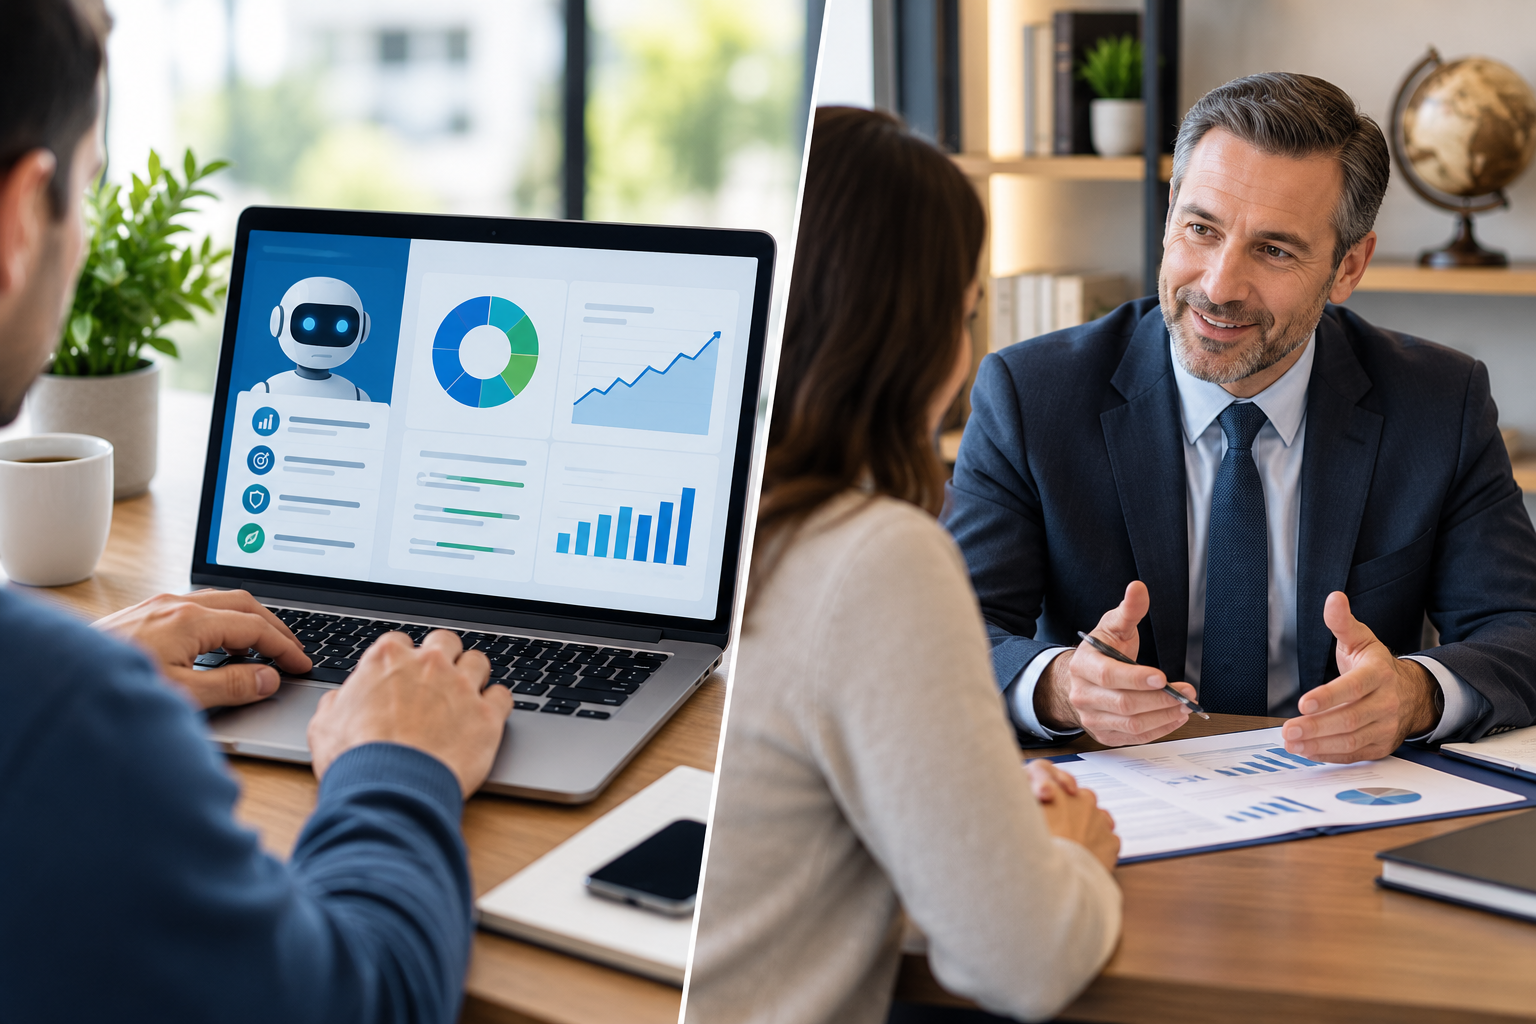
Robo-advisors and traditional financial planning represent two distinct approaches to wealth management. Each has its own advantages and considerations, depending on your financial situation and preferences.
What Are Robo-Advisors?
Robo-advisors are automated, algorithm-driven platforms that provide financial advice and investment management with minimal human involvement. These platforms use algorithms to build and manage portfolios based on your risk tolerance, financial goals, and time horizon.
- How They Work: After answering a series of questions about your financial situation, risk tolerance, and goals, robo-advisors use algorithms to recommend an investment portfolio that typically consists of low-cost exchange-traded funds (ETFs) and index funds. The system automatically rebalances your portfolio as needed and adjusts based on market conditions.
- Advantages of Robo-Advisors:
- Low Fees: Robo-advisors typically charge lower fees compared to traditional financial advisors since there is minimal human involvement.
- Ease of Use: These platforms are user-friendly and accessible, allowing you to start investing quickly and without a lot of paperwork.
- Automated Rebalancing: Robo-advisors automatically manage your portfolio and rebalance it as needed, taking a hands-off approach to investing.
- Limitations of Robo-Advisors:
- Lack of Personalized Advice: Robo-advisors may not provide the personalized advice needed for complex financial situations.
- Limited Human Interaction: If you prefer discussing your financial goals and concerns with a person, the limited human interaction of a robo-advisor may be a disadvantage.
Traditional Financial Planning:
Traditional financial advisors, on the other hand, offer a more personalized, comprehensive approach to wealth management. They can provide advice on a wide range of financial topics, from investment strategies to tax planning and estate management.
- Advantages of Traditional Financial Planning:
- Personalized Service: A human advisor can create a customized plan based on your unique financial situation and goals. They can offer advice on tax strategies, insurance, estate planning, and other aspects of your financial life.
- Comprehensive Planning: Traditional financial advisors can provide a more holistic approach to managing your finances, often helping with more than just investing.
- Human Touch: Advisors can provide guidance during times of uncertainty and can help with complex financial decisions that may not be suitable for an algorithm.
- Limitations of Traditional Financial Planning:
- Higher Fees: Traditional advisors typically charge higher fees compared to robo-advisors, especially if they offer full-service wealth management.
- Accessibility: Finding and working with a traditional financial advisor may require more effort and may not be as accessible for individuals with smaller portfolios or those looking for basic advice.
Which Option is Right for You?
- Robo-Advisors are a good fit if you:
- Have a smaller portfolio and want a low-cost, automated solution.
- Are comfortable with a more hands-off approach to investing.
- Don’t need personalized financial advice or in-depth planning.
- Traditional Financial Advisors are a better fit if you:
- Have more complex financial needs, such as tax planning, estate planning, or retirement strategy.
- Want personalized, ongoing advice and human interaction.
- Are looking to develop a comprehensive financial plan that addresses all aspects of your financial life.
Portfolio Management and Rebalancing
Portfolio management and rebalancing are essential components of any investment strategy. Properly managing your portfolio ensures that your investments are aligned with your financial goals, risk tolerance, and time horizon.
What is Portfolio Management?
Portfolio management refers to the process of creating and managing an investment portfolio to meet specific financial goals. The key elements of portfolio management include:
- Asset Allocation: The distribution of your investments across different asset classes (stocks, bonds, real estate, etc.) based on your risk tolerance and investment goals.
- Diversification: Spreading your investments across different sectors, industries, and geographic regions to reduce risk and improve potential returns.
- Risk Management: Adjusting the risk level of your portfolio to align with your financial goals and time horizon. For example, a more aggressive portfolio might be appropriate for younger investors, while a conservative portfolio might suit someone nearing retirement.
Rebalancing Your Portfolio:
Rebalancing involves adjusting the allocation of assets in your portfolio to maintain your desired level of risk. Over time, certain investments may grow faster than others, causing your portfolio’s asset allocation to shift.
- Why Rebalance? Rebalancing ensures that your portfolio stays aligned with your goals and risk tolerance. If a portion of your portfolio has grown significantly (e.g., stocks have outperformed bonds), your portfolio may become riskier than intended. Rebalancing helps bring it back to its target allocation.
- How Often to Rebalance? Most experts recommend reviewing your portfolio annually or semi-annually. However, if there are significant market changes or life events (like retirement or a large financial windfall), rebalancing may be necessary sooner.
- Rebalancing Strategies:
- Calendar-Based Rebalancing: This involves rebalancing your portfolio at set intervals, such as annually or quarterly.
- Threshold-Based Rebalancing: Rebalance when an asset class deviates by a certain percentage from its target allocation (e.g., if stocks account for more than 5% of your target allocation).
Tax-Efficient Portfolio Management:
Tax-efficient investing is about managing your investments in a way that minimizes taxes. This can include strategies like tax-loss harvesting, utilizing tax-advantaged accounts (e.g., IRAs, 401(k)s), and holding investments for the long term to benefit from lower capital gains taxes.
Conclusion
Wealth management and advisory services are vital for individuals who want to optimize their financial strategies and achieve long-term goals. Whether working with a traditional financial advisor, using a robo-advisor, or managing your portfolio independently, understanding the basics of financial planning, portfolio management, and rebalancing is key. By partnering with the right advisor and regularly reviewing your investment strategy, you can ensure that your wealth is managed effectively and aligned with your goals.